
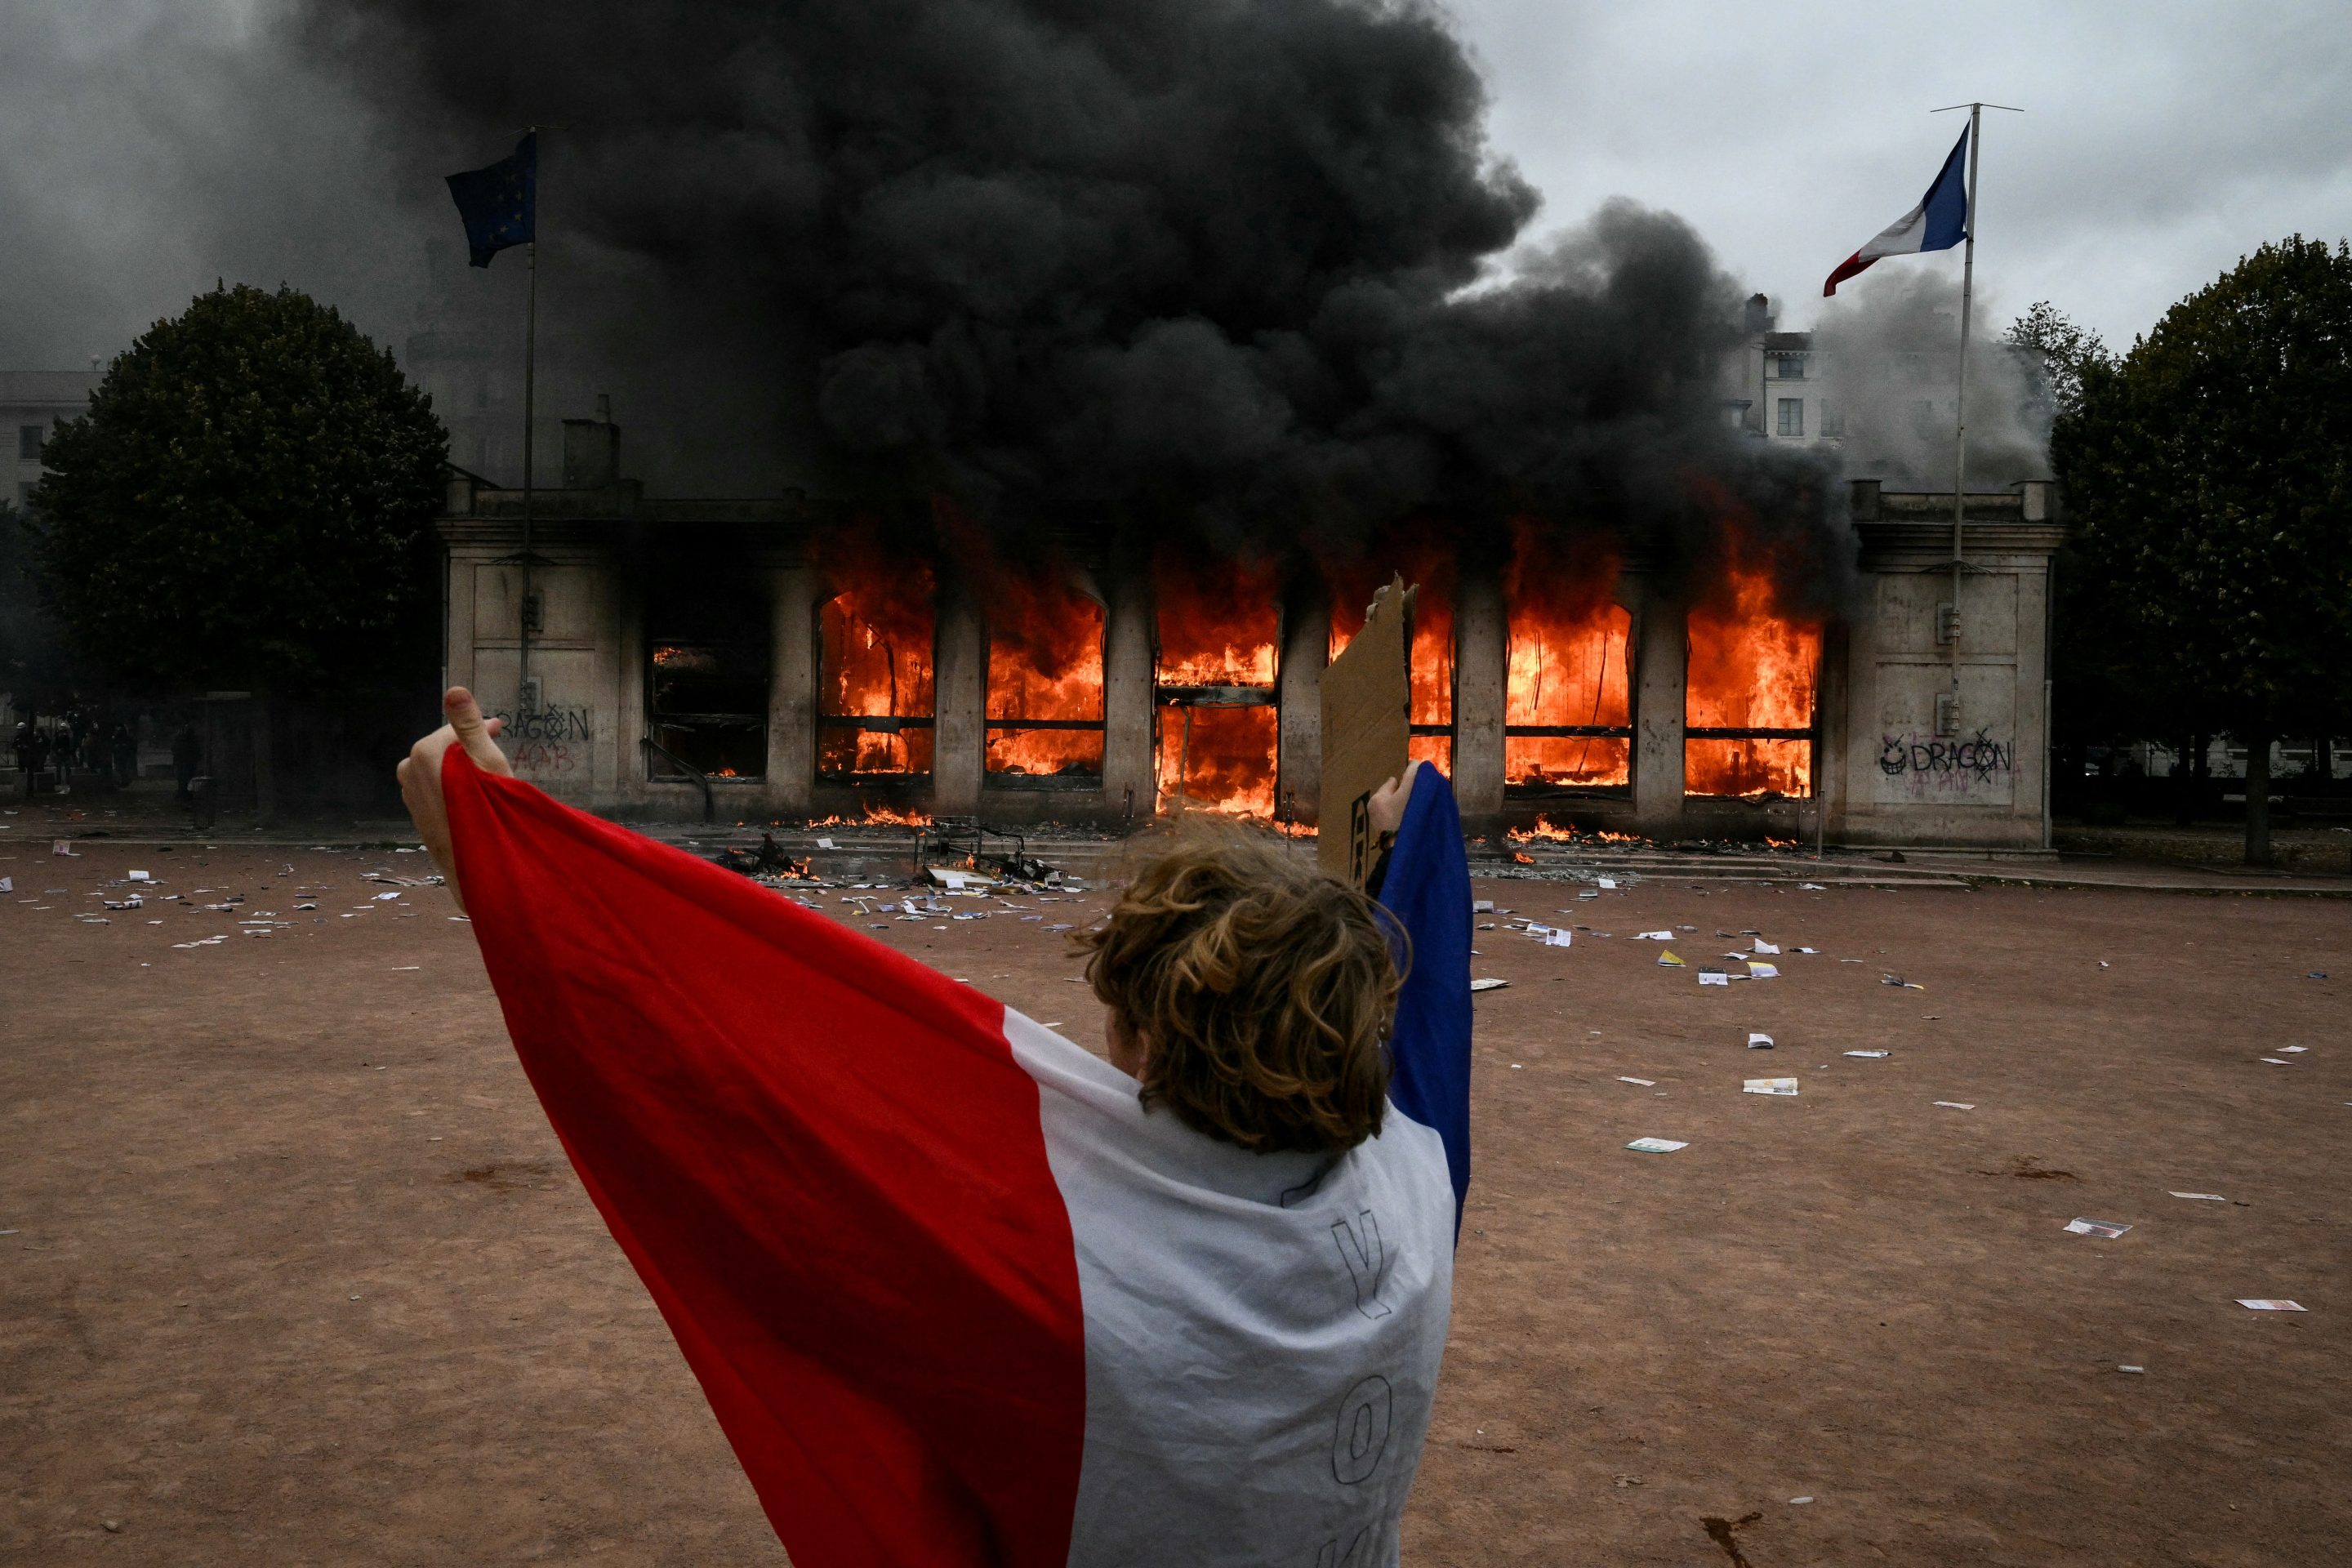
Nationwide protests over the high cost of living roiled France on Saturday, adding to turmoil over public spending and debt ahead of a critical vote in the National Assembly.
Rioting broke out in some cities as luxury boutiques and supermarkets were looted while public buildings were defaced and even set on fire.
That followed mass demonstrations earlier this month, with students decrying run-down classrooms, missing teachers, and buildings that aren’t equipped for rising temperatures. Protestors blamed years of underinvestment in public education.
At the same time, France’s looming debt has sent bond yields to the highest levels in 24 years, flashing warning signs not seen since the eurozone debt crisis in 2011.
With far-right and far-left candidates in the lead to become France’s next president in the spring, markets are losing confidence that either side will take the painful steps necessary to rein in the deficit.
For Mujtaba Rahman, managing director for Europe at Eurasia Group, France is suffering from a crisis of liberal democracy, a crisis of fiscal mismanagement, and a crisis of youth disaffection.
“But the fiscal crisis is the most dangerous, underlying many of the country’s woes and threatening to bring it to ruin,” he wrote in a New York Times op-ed on Thursday. “France, truly, is on the brink.”
The crises are also related to each other. For instance, Rahman pointed out that while France’s education spending tops the European Union average, more than a quarter of the money pays for pensions of retired teachers.
Nobel laureate Paul Krugman similarly drew a straight line from France’s retirement largesse to the student unrest. Due to its very generous government pension plan, education spending has suffered, meaning France is effectively subsidizing older French at the expense of everyone else, he wrote in a Substack post last week.
France’s public debt is now a record $4 trillion, or 119% of GDP—the highest ratio since the immediate aftermath of World War II.
While the pandemic as well as the Ukraine and Iran wars worsened France’s fiscal picture, President Emmanuel Macron has also pulled back from reforms meant to rein in the debt.
Sébastien Lecornu, the latest in a revolving door of prime ministers, has proposed a 2027 budget that would modestly bring the deficit down to 5% of GDP from 5.4%, and faces a first critical vote in the National Assembly on Tuesday.
“If his government fails to pass the budget, the cost of servicing French debt may explode,” Rahman predicted. “France could be forced to seek assistance from the International Monetary Fund and to pray for it from the European Central Bank — a humiliation for the world’s seventh-biggest economy.”
The market’s distrust of France is more political than economic, fearing it has become ungovernable with the extreme left and right unlikely to make necessary changes, he added.
Indeed, far-right leader Marine Le Pen has vowed to roll back the official retirement age to 62 and even previously suggested dropping it to as low as 60. Meanwhile, far-left presidential candidate Jean-Luc Mélenchon is campaigning on a plan to have the central bank simply cancel its holdings of French debt.
Such positions help explain why bond investors have sent France’s borrowing costs to sky-high levels, Rahman said. “The country, they fear, is becoming socially volatile and institutionally paralyzed.”
In fact, the presidential election in May will not even be that decisive for financial markets, as a legislative election in June might fail to produce a parliamentary majority for the new president, setting up further political gridlock, he said.
France could avoid imminent catastrophe this coming week if Le Pen orders her allies in the Assembly to abstain on the budget, allowing it to pass.
“That may avert, for now, the kind of meltdown suffered by Greece after the financial crash. But France is no longer in control of its destiny,” Rahman warned.
An explosion in borrowing costs would signal that France is at the mercy of the bond market, which has started pricing in growing odds of a debt default. That’s similar to how the United Kingdom is effectively in thrall to so-called bond vigilantes.
Thierry Wizman, global FX and rates strategist at Macquarie Group, argued in a note Tuesday that a series of convulsions would have to occur for France to get its act together and appease the bond market.
That could include a no-confidence vote that leaves France with no governance from the Assembly, a Moody’s credit downgrade, a widening of street protests and violence, a sharper and contagious spike in France’s bond yield spread, and the election of Le Pen as president.
The European Central Bank also wouldn’t come to the rescue quickly for fear of encouraging “moral hazard,” and other bailout mechanisms lack the firepower for an economy as large as France’s, Wizman argued.
“Either way, it would seem that one would have to go through the valley before getting to the other side of the fiscal responsibility gap,” he added. “And only after all that transformational pain of the next few months may France find its spine and commit to austerity.”
This story was originally featured on Fortune.com



Leave a comment